A TFSA successor holder is your spouse or common-law partner, and if properly designated, the TFSA transfers tax-free and generally bypasses probate. If you are a successor holder status means the survivor simply becomes the new account holder at the moment of death, with the account’s value and future growth staying sheltered. Quebec does not recognize this designation, so survivors there rely on a different route entirely.
TL;DR:
- Successor holders must be named directly on the TFSA contract to ensure the account transfers seamlessly and remains tax-exempt after death.
- Quebec residents cannot recognize successor holder designations and must use the exempt-contribution process within strict deadlines to avoid taxation.
- Designating a successor holder generally prevents probate and tax on growth, unlike beneficiary designations that may incur taxes on post-death earnings.
- Confirm with your issuer annually that successor holder details are current, especially after major life changes or moving provinces to avoid processing issues.
- Acting promptly with the issuer after death helps preserve the TFSA’s tax benefits and prevents taxable windows or penalties from excess contributions.
Table of Contents
- What a successor holder is and who qualifies
- Successor holder versus beneficiary versus the estate
- Quebec’s exception and the exempt-contribution route
- How to name a successor holder the right way
- What survivors and executors should do right after death
- Pitfalls that create unexpected tax bills
- A planner’s view on TFSA succession for couples
- How we help you plan beyond the TFSA
- FAQ
- Sources
What a successor holder is and who qualifies
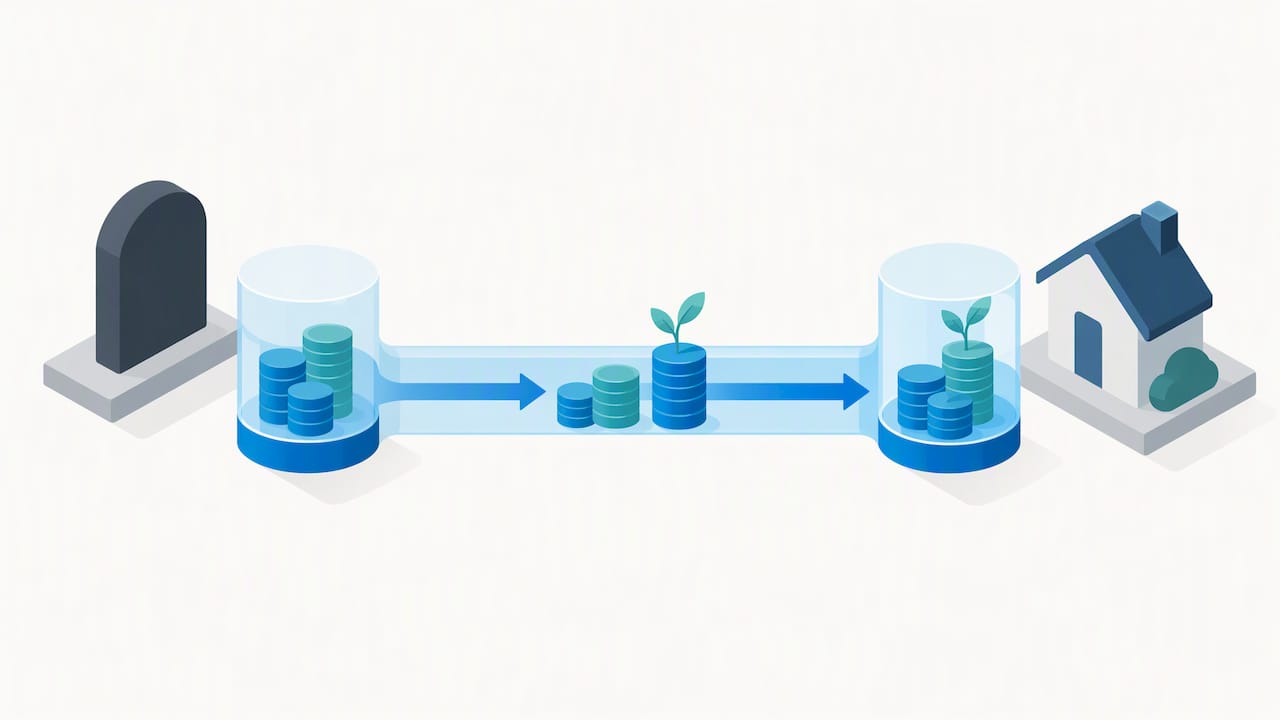
When a TFSA holder names a spouse or common-law partner as successor holder, the CRA treats that survivor as stepping directly into the deceased’s shoes. There is no gap in ownership and no interruption in tax-sheltered status. The successor holder becomes the new account holder immediately, and both the value at death and any income earned afterward remain exempt from tax.
Only a spouse or common-law partner can hold this status. Anyone else named on a TFSA, a child, a sibling, a friend, is a designated beneficiary instead, which carries different tax consequences. The survivor also needs a Social Insurance Number to be recognized; a non-resident survivor can use an Individual Tax Number instead.
Where the designation gets recorded matters more than most people realize:
- The TFSA contract itself is the safest place to name a successor holder, since issuers act on it directly without needing outside legal proof.
- A will can also name a successor holder, but only if it explicitly grants the survivor “all rights of ownership,” including the unconditional right to revoke prior beneficiary designations.
- Issuers often require an in-kind transfer or a new account setup rather than a simple renaming, which affects how quickly the survivor can trade or withdraw.
Pro Tip: Call your TFSA issuer and confirm, in writing, how they record successor holder designations. Some require a specific form rather than relying on the contract alone.
Successor holder versus beneficiary versus the estate
The designation you choose changes who pays tax and whether probate applies. These are three different outcomes, not variations of the same thing.
- Successor holder: the TFSA continues as-is, income earned after death stays tax-exempt, and the account generally bypasses probate.
- Named beneficiary (not successor): the fair market value at death typically passes tax-free, but any growth between the date of death and the date of payout becomes taxable to the beneficiary.
- No designation, or the estate as beneficiary: the TFSA becomes part of the estate, probate rules apply where the province requires them, and any post-death growth is taxable to the estate or its beneficiaries.
Consider a simplified scenario: say a TFSA holds $80,000 at the date of death and the issuer takes four months to process the transfer, during which the account earns $1,200 in growth. A successor holder keeps that $1,200 tax-free because the account never stopped being a TFSA. A designated beneficiary who receives a lump-sum payout instead would owe tax on that $1,200 as income. If the account had no valid designation at all, the full $80,000 could also face probate fees, depending on the province, on top of the same tax exposure on growth.
That gap, tax-free growth versus taxable growth, plus avoided versus incurred probate costs, is the entire reason the successor holder designation exists.
Quebec’s exception and the exempt-contribution route
Quebec is the one province where successor holder designations for TFSAs simply are not recognized. A surviving spouse in Quebec cannot step into the deceased’s TFSA the way a spouse in Ontario or Alberta can. Instead, Quebec survivors who receive TFSA proceeds use the exempt-contribution process to preserve the tax-free treatment.
The timing requirements are strict:
- The survivor must contribute the amount received into their own TFSA by December 31 of the year following the year of death.
- The survivor must file Form RC240, Designation of an Exempt Contribution, within 30 days of making that contribution.
- The contribution must be documented as coming from the deceased’s TFSA proceeds, not treated as a fresh deposit against the survivor’s own room.
A missed RC240 deadline or a late contribution turns what should have been tax-free into taxable investment income for the survivor, according to CRA guidance on designated beneficiaries.
The most common pitfall is simple delay: executors settling an estate often take months to distribute TFSA proceeds, leaving a narrow window once funds finally arrive. Survivors in Quebec should start tracking the December 31 deadline the moment they learn a TFSA payout is coming, not after the check arrives.
How to name a successor holder the right way
Naming a successor holder correctly takes a few concrete steps, and skipping any one of them can leave the designation unenforceable when it matters.
- Locate your TFSA contract and check whether it has a specific successor holder field, separate from the beneficiary field.
- Contact your issuer directly to update or confirm the designation rather than assuming your will covers it.
- If you do rely on a will, make sure it uses language granting the survivor “all rights of ownership,” including the unconditional right to revoke beneficiary designations, since vague wording gives issuers grounds to refuse recognition.
- Record your spouse’s Social Insurance Number on file with the issuer, or arrange an Individual Tax Number if they are a non-resident.
- Ask the issuer what supporting documents they will require at the time of transfer, so there are no surprises for your executor later.
Pro Tip: Review your TFSA successor holder designation every year, especially after a marriage, separation, or a move to or from Quebec, since issuers sometimes lose or fail to carry forward older paperwork. Our guide to naming a TFSA beneficiary walks through the contract fields step by step.
Annual review matters more than it sounds. Issuers merge, update systems, and occasionally fail to migrate successor holder fields correctly during a platform change, so a designation made a decade ago is worth confirming still shows up in the current system.
What survivors and executors should do right after death
Acting quickly after a TFSA holder’s death protects the tax-free status of the account and avoids unnecessary paperwork delays.
- Notify the TFSA issuer as soon as possible and request the specific successor holder transfer forms, not the general beneficiary claim forms.
- Provide the death certificate, the survivor’s SIN or ITN, and standard identity documents the issuer requests.
- Ask whether the issuer can do an in-kind transfer of existing investments or whether the account must be liquidated and reopened, since liquidation can trigger a brief taxable window.
- If a payout does happen instead of a direct transfer, record the exact payout date and track any investment growth between the date of death and the payout, since that growth may be taxable.
- Consult a lawyer or tax advisor when the successor holder status is unclear, when a trust is involved, or when the deceased’s TFSA had an excess contribution amount at death.
Executors juggling multiple accounts often treat TFSAs like any other asset, which is where tax-free status gets lost through simple inattention. Our executor’s checklist for Canada covers the broader sequence of duties beyond the TFSA itself.
Pitfalls that create unexpected tax bills
A few situations turn what should be a clean, tax-free transfer into a costly mistake.
- If the deceased had an excess TFSA amount at death, the successor holder is deemed to make a contribution equal to that excess on the first day of the month after death, which can push the survivor’s own TFSA into excess territory.
- An excess TFSA amount triggers a penalty of 1% per month on the excess until it is withdrawn or absorbed by new contribution room, per CRA’s successor holder guidance.
- A TFSA held in trust arrangement may not transfer the way a standard successor holder designation does; the trust’s own terms and provincial law determine whether the survivor can step in at all.
- Issuer processing delays, requiring new account setup or temporary payouts, can create a taxable window even when the CRA already recognizes the successor holder, so early contact with the issuer matters.
- Survivors assuming a TFSA should check their own available contribution room before treating the account as fully theirs, since they do not inherit the deceased’s unused room.
Our piece on TFSA contribution limits breaks down how room accumulates and how to spot an excess before it costs you.
A planner’s view on TFSA succession for couples
Most couples name a successor holder once, at account opening, and never look at it again. That single oversight causes more avoidable probate exposure than almost any other estate planning gap we see, because people assume a will automatically covers it. It does not, and issuers are increasingly strict about requiring the contract designation itself.
The priority is straightforward: name the successor holder directly on the TFSA contract, then separately confirm your will’s language does not contradict or weaken that designation. Life insurance and broader estate planning still matter here, since they provide liquidity that covers probate costs and final expenses on assets that are not as cleanly structured as a TFSA. A TFSA solves one piece of the puzzle; the rest of the estate usually needs its own plan.
— Frank
How we help you plan beyond the TFSA
A TFSA successor holder designation handles one account well, but most estates include assets that still face probate delays or tax exposure, which is where estate planning and the right insurance coverage fill the gap.
- We help you review how your TFSA, will, and other accounts work together to coordinate your estate planning.
- We discuss insurance coverage options to help with estate liquidity for immediate costs.
- We provide guidance on estate planning, retirement planning, and tax planning in a coordinated manner.
If you want a second set of eyes on your TFSA designation and the rest of your estate plan, visit our estate planning services page to schedule a review.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
How do I name my TFSA successor holder?
You name a successor holder directly through your TFSA issuer’s contract, not just in your will, since issuers act on the contract designation first. Contact your financial institution to confirm they have a dedicated successor holder field and that your spouse’s SIN is on file.
Is it better to have a successor or a beneficiary?
A successor holder designation is generally better for a spouse or common-law partner because the account stays open, continues earning tax-free, and typically bypasses probate. A beneficiary designation only protects the value at the date of death; any growth afterward becomes taxable to that beneficiary.
Do beneficiaries pay tax on TFSA inheritance?
The fair market value of the TFSA at the date of death generally passes to a designated beneficiary tax-free. Any investment growth that occurs between the date of death and the date the funds are actually paid out, however, is taxable to the beneficiary as income.
What happens if I don’t name a successor holder or beneficiary?
Without a valid designation, the TFSA becomes part of the estate, which can mean probate fees depending on the province and taxable growth on any income earned after death. Naming a successor holder or beneficiary directly on the TFSA contract avoids this outcome for a spouse or named heir.
Can a Quebec resident still use a TFSA successor holder?
Quebec does not recognize the TFSA successor holder designation, so a surviving spouse there cannot simply step into ownership of the account. Instead, Quebec survivors can contribute the TFSA proceeds into their own TFSA and file Form RC240 within 30 days to preserve the tax-free treatment.