An inter vivos trust, often called a living trust, is created while you’re alive and holds assets you transfer into it now. A testamentary trust is created by your will and only comes into existence after you die. The practical difference for Canadians comes down to who controls the assets and when, plus how the Canada Revenue Agency taxes each one and whether probate applies.
TL;DR:
- Most Canadian trusts created during life are irrevocable and used for asset protection or multigenerational planning, while revocable trusts are more flexible but less protected.
- Tax rates on trusts changed in 2016, making most testamentary and non-grandfathered inter vivos trusts subject to the top federal rate after 2015, except for qualified disability trusts and graduated rate estates during their specific windows.
- Funding an inter vivos trust involves retitling assets and can trigger immediate capital gains tax, whereas testamentary trusts usually do not trigger taxes at creation but pass assets through probate.
- Using joint ownership as a probate avoidance strategy risks unintended tax consequences and court challenges, especially if ownership was not properly structured or documented as a gift.
- The choice between trust types depends on factors like probate fees, incapacity planning, beneficiary needs, tax goals, and asset types; consulting legal and tax professionals is essential.
Table of Contents
- Types of trusts and how Canadian estate plans use them
- How does Canada tax inter vivos and testamentary trusts differently?
- Weighing the trade-offs: pros and cons of each trust type
- What should you ask your lawyer before choosing a trust?
- Why joint ownership isn’t the trust alternative it seems
- Setting up a trust and handling it after death
- How insurance and trusts work together in an estate plan
- What actually drives the trust decision in real families
- Plan your estate with support built around Canadian families
- FAQ
- Sources
Types of trusts and how Canadian estate plans use them
An inter vivos trust is set up and funded during the settlor’s lifetime. You draft a trust deed, name a trustee, and transfer ownership of property, investments, or a business interest into the trust. Once that transfer happens, the assets legally belong to the trust rather than to you personally, which is the entire point: it separates legal ownership from your personal estate. According to CRA’s trust definitions, an inter vivos trust is any trust that is not a testamentary trust, meaning it exists independently of a death.
These trusts come in two forms. A revocable trust lets the settlor change or dissolve it later, which gives flexibility but offers weaker creditor protection since the settlor still effectively controls the assets. An irrevocable trust locks the arrangement in place: once funded, the settlor generally cannot undo it, which strengthens asset protection but removes future flexibility. Most Canadian estate lawyers lean toward irrevocable structures when the goal is creditor protection or multigenerational tax planning, while revocable arrangements suit people who want a tool for incapacity planning without giving up control today.
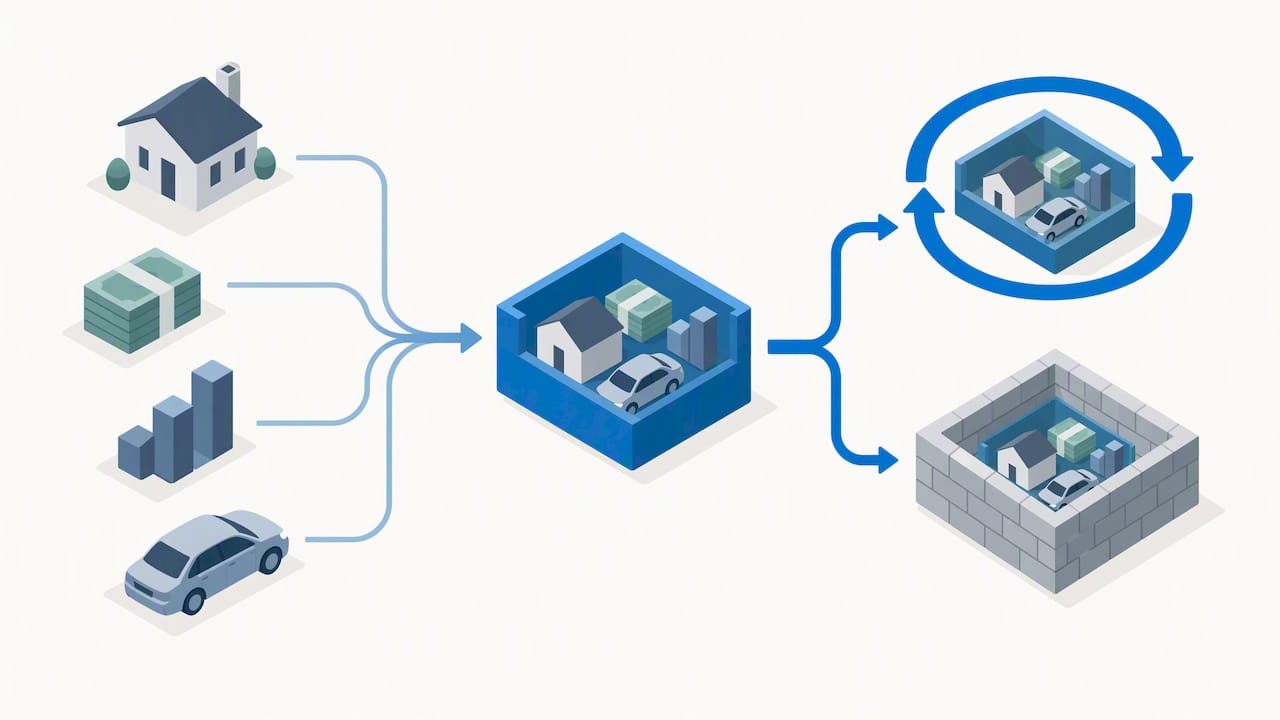
A testamentary trust works differently. There’s no separate deed to sign while you’re alive, no funding step to complete now. The will itself is the trust document, and the executor acts as the first trustee unless the will names someone else.
Several subtypes matter for Canadian tax and estate planning:
- Spousal or common-law partner trusts let a deceased person’s assets pass to a trust for their spouse’s benefit, often deferring capital gains tax until the spouse’s death.
- Qualified disability trusts (QDTs) are testamentary trusts for beneficiaries eligible for the disability tax credit, and they retain access to graduated tax rates even after the 2016 rule changes.
- Graduated rate estates (GREs) are a special category of testamentary trust tied to the deceased’s own estate, available only for a limited window after death.
A quick example helps make the distinction concrete. Say a business owner in her fifties sets up an inter vivos trust and transfers shares of a holding company into it, naming her adult children as beneficiaries while she continues managing the business as trustee. If she becomes incapacitated, the trust keeps functioning without a court-appointed guardian. Compare that to a parent of young children whose will creates a testamentary trust that only activates on death, holding life insurance proceeds and investment assets for the kids until they reach a specified age, with a trustee controlling distributions in the meantime.
How does Canada tax inter vivos and testamentary trusts differently?
Tax treatment is often the deciding factor between these two structures, and it changed significantly in 2016. Before that year, testamentary trusts enjoyed graduated tax rates similar to individuals, which made them a popular income-splitting tool. The federal government’s 2014 budget guidance on graduated rate taxation confirms that for taxation years after 2015 and 2016, most testamentary trusts and non-grandfathered inter vivos trusts pay federal tax at the top flat marginal rate rather than on a graduated scale.
Two exceptions survived the reform: graduated rate estates and qualified disability trusts. A GRE is the estate of a deceased individual, and it can use graduated tax rates for up to 36 months following the date of death, according to CRA’s guidance on trust types. After that 36-month window closes, any trust that continues to hold estate assets reverts to the flat top rate unless it qualifies as a QDT.
36 months is the entire window a graduated rate estate has to access progressive tax rates before CRA treats it like any other trust taxed at the top bracket, according to CRA’s trust guidance. That timeline matters enormously for executors deciding when to wind up an estate or distribute remaining assets, since delaying past the 36-month mark can mean a meaningfully higher tax bill on any income the estate continues to earn.
Filing obligations follow from this classification. Trustees of both inter vivos and testamentary trusts generally must file a T3 trust income tax return reporting the trust’s income and allocations to beneficiaries. The T3 trust guide explains filing requirements for each trust type and the special reporting rules that apply depending on classification, including instalment obligations once a trust generates ongoing income and Part XII.2 tax, which applies in certain cases involving designated beneficiaries.
A few practical consequences follow from these rules:
- An inter vivos trust transfer can trigger an immediate deemed disposition, meaning capital gains tax may apply the moment you fund the trust, not later.
- A testamentary trust generally doesn’t trigger immediate tax on creation since assets pass through the estate first, though the estate itself may owe tax on income earned before distribution.
- A testamentary trust can unexpectedly convert into an inter vivos trust if it incurs a debt owed to a beneficiary or fails to distribute assets as the will directs, a shift CRA’s guidance flags as carrying its own tax consequences.
Recent federal updates to trust tax rates are tracked in detail by resources such as this tax rate change log, which is useful if you want to confirm current figures before a planning meeting.
Weighing the trade-offs: pros and cons of each trust type
Choosing between these structures means weighing control, cost, and tax exposure against your actual goals.
- Inter vivos trust advantages: they provide continuity if you become incapacitated, since a successor trustee can step in without court involvement; a properly funded trust bypasses probate on those specific assets; and they let you observe how the trust functions while you’re still around to adjust the plan.
- Inter vivos trust disadvantages: funding the trust takes real effort, since every asset must be formally retitled into the trust’s name; transferring appreciated property can trigger an immediate capital gain; and ongoing trustee and accounting fees apply even while you’re alive and healthy.
- Testamentary trust advantages: you retain full control over assets until death, with no funding step required now; they let you structure long-term distributions for minor children or a beneficiary who needs protection; and a GRE or QDT can access graduated tax rates for a defined period.
- Testamentary trust disadvantages: the assets that fund it typically still pass through probate before the trust takes effect, so provincial probate fees apply; trustees face new filing and administration duties right when the family is already managing a death; and once the GRE window closes, the trust is taxed at the flat top rate like most others.
What should you ask your lawyer before choosing a trust?
The right structure depends on specifics that only you, a lawyer, and often an accountant can weigh together. Start with these criteria:
- Probate exposure: what would your estate actually pay in probate fees in your province if these assets passed through a will instead of a trust.
- Incapacity risk: whether a sudden illness or cognitive decline would leave assets unmanaged without a trustee already in place.
- Beneficiary needs: whether minors, a disabled beneficiary, or someone who shouldn’t receive a lump sum outright are involved.
- Tax goals: whether the priority is minimizing probate, deferring capital gains, or accessing a GRE’s graduated rates.
- Asset type: certain property, like shares in a private company or real estate with a mortgage, is harder to transfer into a trust without triggering tax or lender consent issues.
When you sit down with a lawyer or accountant, bring specific questions rather than general ones: what will it cost to fund this trust now versus leaving the asset in my estate, what tax consequences arise the moment I transfer this property, what powers and fees will the trustee have, how will this affect my eligibility for income-tested government benefits, and how does this interact with the beneficiary designations already on my registered accounts and life insurance.
Watch for a few warning signs before committing to a plan. Adding a child’s name to title as a quick fix, without legal advice, can trigger a deemed disposition and expose the property to that child’s creditors or a divorce settlement. An unfunded living trust (one that exists on paper but never actually receives the assets) does nothing to avoid probate, since those assets still pass through your estate. And any plan sold purely as a way to dodge probate, without discussing the tax trade-offs, deserves a second opinion.
Pro Tip: Ask your advisor to run the numbers on both probate fees and capital gains tax before you transfer an asset, since the cheaper option on one side is sometimes the costlier one on the other.
Why joint ownership isn’t the trust alternative it seems
Many Canadians try to sidestep trusts and probate altogether by simply adding a spouse or adult child to a property title or bank account. It’s worth understanding exactly what that does and doesn’t accomplish, since the two forms of joint ownership behave very differently.
Joint tenancy with right of survivorship means that when one owner dies, the surviving owner automatically takes full ownership, often bypassing probate on that specific asset. Tenancy in common, by contrast, means each owner holds a distinct share that passes through their estate (and often through probate) when they die, rather than going automatically to the other owner.
The catch with joint tenancy is that courts don’t always take the surviving owner’s claim at face value. According to practitioner guidance on joint ownership risks in Ontario, Canadian courts often apply a resulting trust presumption when a parent adds an adult child to title without clear documentation of intent, meaning the child may be found to hold the asset in trust for the estate rather than owning it outright. That same guidance notes that adding someone to title can trigger a deemed disposition and capital gains tax immediately, and it can expose the asset to the new co-owner’s creditors or a family-law claim if that person later divorces or faces a lawsuit.
- Right of survivorship can move an asset outside your estate instantly, but only if the ownership was properly structured and intended as a gift.
- Adding a name to title is not a substitute for legal advice, since the tax and creditor consequences often outweigh the probate savings.
- A trust usually gives more precise control than joint ownership when beneficiaries are minors, have creditor risk, or when you want the arrangement to survive scrutiny after you’re gone.
For a closer look at probate-specific strategies and their limits, see how to avoid probate in Ontario or the broader guide to avoiding probate in Canada.
Setting up a trust and handling it after death
Creating either trust follows a fairly predictable sequence, though the steps and timing differ.
- Draft the trust document. For an inter vivos trust, this is a standalone deed; for a testamentary trust, it’s built into the will’s wording, specifying the trustee, beneficiaries, and distribution terms.
- Fund the trust. An inter vivos trust needs assets formally retitled into its name now. A testamentary trust gets funded automatically when the executor transfers estate assets to it after probate and estate administration.
- Name trustees and successor trustees. Both structures need someone willing and able to manage assets and file tax returns on the trust’s behalf.
- Handle post-death administration. Once a death occurs, the executor gathers assets, pays debts, applies for probate where required, and then transfers remaining property into any testamentary trust named in the will.
- File the T3 return. Trustees of an active trust must determine their filing obligations under the T3 trust guide, which covers deadlines and reporting rules for both trust categories.
Costs vary by complexity: legal drafting fees for the trust document or will, ongoing trustee compensation (often a percentage of trust assets), and annual accounting fees for T3 preparation. The most common mistake is leaving an inter vivos trust unfunded, meaning the deed exists but no assets were ever transferred into it, which provides none of the probate benefits it was meant to deliver. A close second is forgetting to update beneficiary designations on registered accounts and insurance policies so they align with the overall estate plan rather than contradicting it.
How insurance and trusts work together in an estate plan
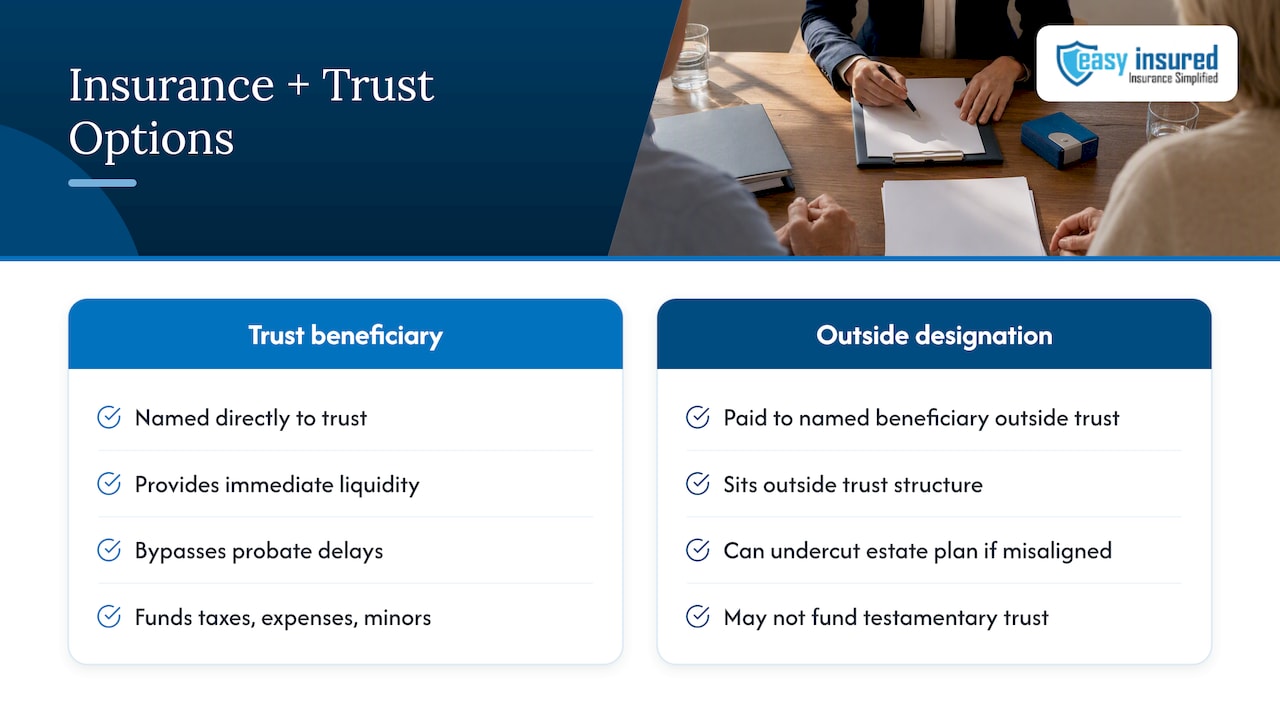
Life insurance proceeds often fund a testamentary trust directly, naming the trust as beneficiary so the payout provides immediate liquidity for a young family without passing through probate delays. That liquidity can cover estate taxes, ongoing household expenses, or a lump sum held in trust for minor children until they reach an appropriate age.
Beneficiary designations on insurance policies and registered accounts sit outside the trust structure but need to work alongside it, since a misaligned designation can undercut the entire estate plan. Easy-Insured supports Canadian families and business owners working through these decisions as part of its estate planning services, and the related overview on estate planning strategies to reduce taxes walks through how insurance and trusts interact in a broader tax plan.
Frank writes on estate and financial planning topics for Canadian families and business owners, focusing on how insurance, trusts, and tax rules intersect in practical estate plans.
What actually drives the trust decision in real families
A business owner in her sixties worried about a future stroke or dementia usually benefits more from an inter vivos trust, since it keeps a successor trustee ready to manage assets without a court application. A parent with two kids under ten is often better served by a testamentary trust funded by life insurance, since it needs no funding effort now and only activates when the family actually needs it.
Neither choice is universal, and the tax and probate consequences are specific enough that guessing wrong is expensive. Talk to a Canadian estate lawyer and a tax advisor before committing either way.
— Frank
Plan your estate with support built around Canadian families
Choosing between an inter vivos trust and a testamentary trust is only one piece of a broader estate plan, and insurance decisions often determine whether that plan actually works when your family needs it. Estate planning services can connect Canadian business owners and families with a certified financial planner who can walk through how trusts, life insurance, and beneficiary designations fit together.
- Review your current life insurance and beneficiary designations against your trust or will structure.
- Get a second opinion on whether your assets would actually avoid probate under your current plan.
- Ask about final expense and whole life options that can fund a testamentary trust directly.
Visit the estate planning services page to book a conversation about how your insurance and trust plans fit together.
FAQ
What are the disadvantages of an inter vivos trust?
Funding an inter vivos trust requires formally retitling each asset, which takes time and can trigger an immediate capital gain on appreciated property. Ongoing trustee and accounting costs also apply while you’re alive, even if the trust holds relatively simple assets.
What is the difference between an inter vivos trust and a testamentary trust?
An inter vivos trust is created and funded during your lifetime, while a testamentary trust is created by your will and only comes into existence after death, as explained in CRA’s trust definitions. The practical result is that one gives you control and planning flexibility now, while the other only takes effect once your estate is being administered.
What is the disadvantage of a testamentary trust?
Assets destined for a testamentary trust usually pass through probate first, so provincial probate fees still apply before the trust is funded. Once a graduated rate estate’s 36-month window closes, the trust is generally taxed at the flat top federal rate rather than on a graduated scale, under the 2016 tax rule changes.
What are the pros and cons of forming an inter vivos trust in Canada?
The main advantage is continuity during incapacity, since a successor trustee can manage assets without court involvement, and a properly funded trust can bypass probate on those assets. The main drawback is the funding effort involved and the possibility of triggering capital gains tax the moment assets transfer into the trust.