Simplified issue life insurance is generally the better deal if you can pass a short health questionnaire, since it typically comes with higher coverage limits and lower premiums. Guaranteed issue exists for the opposite case: no health questions, no possibility of a decline, but smaller payouts, higher costs per dollar of coverage, and a graded death benefit that limits payouts if you die of natural causes early on. The right choice depends less on preference and more on your actual health history.
TL;DR:
- Simplified issue life insurance offers higher coverage limits and lower premiums than guaranteed issue but still requires answering health questions.
- Guaranteed issue guarantees acceptance for eligible applicants regardless of health, but features lower coverage caps and a graded death benefit during the first two to three years.
- Declines for simplified issue often occur with recent serious health conditions, while guaranteed issue is suitable for those declined elsewhere or needing immediate, small coverage.
- Both options provide quick approval, with simplified issue decisions often made the same day, but guaranteed issue always approves within the age range without assessing health.
- Your choice should depend on your health history, coverage needs, and timeline, with honest answers to health questions being critical to avoid claim issues later.
Table of Contents
- Simplified Issue vs Guaranteed Issue: What Simplified Issue Actually Means
- What Guaranteed Issue Life Insurance Actually Guarantees
- Simplified Issue vs Guaranteed Issue: The Direct Comparison
- How Do You Decide Between the Two?
- Applying and Timelines: What to Expect
- What If Neither No-Exam Option Fits?
- Why Trust This Guide: Author and Publisher Credentials
- Real Scenarios, Real Recommendations
- How Easy-Insured Helps You Choose the Right Path
- Sources
- FAQ
Simplified Issue vs Guaranteed Issue: What Simplified Issue Actually Means
Simplified issue life insurance skips the medical exam but not the questions. You answer a short health questionnaire, typically ten to twenty yes or no items about conditions like cancer, heart disease, or recent hospitalizations, and the insurer may cross check your answers against prescription and medical databases. There’s no needle, no nurse visit, no waiting on lab results.
That distinction matters for pricing. Because insurers still gather health information, they can price risk more accurately than with guaranteed issue, which means simplified issue life insurance typically carries higher coverage maximums and lower premiums than guaranteed issue, even though it still costs more than a fully underwritten policy. Regulators in Canada draw the same line: AMF guidance describes simplified issue as coverage obtained quickly through health questions rather than a physical exam, and notes it isn’t the same thing as instant, no review online issuance in every case. Some applications still get a manual look.
Who gets declined? Insurers reject simplified issue applicants for major red flags: recent cancer treatment, uncontrolled diabetes with complications, a stroke within the past year, or certain mental health hospitalizations. A “yes” answer doesn’t always mean rejection. It often just triggers a follow up question or a lower offer.
- No medical exam, but a health questionnaire is mandatory
- Database checks (prescription history, medical records) can still flag inconsistencies
- Coverage often ranges higher than guaranteed issue, with pricing closer to traditional term
- Declines happen for serious, active, or recent conditions
What Guaranteed Issue Life Insurance Actually Guarantees
Guaranteed issue does exactly what the name promises: automatic acceptance for anyone within the eligible age range, no health questions asked. Guaranteed issue life insurance is built specifically for people who can’t get standard coverage. There’s no questionnaire to fail because there’s no questionnaire.
The tradeoff is real and it’s not small. Guaranteed issue policies commonly target older applicants within a certain age range and cap coverage far lower than simplified issue, often in the range used for final expenses rather than income replacement. Premiums run higher per dollar of coverage, and most policies include a graded death benefit: if you die of natural causes within the first two to three years, your beneficiaries typically get back only the premiums paid, plus interest, rather than the full face value. Accidental death is usually paid in full from day one.
Guaranteed issue makes the most sense in a narrow set of situations:
- You’ve been declined for simplified issue or traditional coverage in the past
- You have a serious or terminal diagnosis and need something in place now
- You need a small policy specifically to cover funeral and final expenses
- Time matters more than price, and acceptance can’t be a question mark
Insurers use guaranteed issue as a last resort product on purpose. It lets them offer something to nearly everyone without taking on unlimited risk, which is why the face amounts stay modest and the graded period exists in the first place.
Simplified Issue vs Guaranteed Issue: The Direct Comparison
Put side by side, the two products split cleanly along a few axes that actually decide which one you should apply for.
Approval: Simplified issue is conditional. You could be declined based on your questionnaire answers. Guaranteed issue is, as the name says, guaranteed for anyone in the eligible age bracket.
Cost and coverage: Simplified issue usually supports higher face amounts at lower rates than guaranteed issue, because insurers have more information to price the risk. Guaranteed issue caps coverage lower and charges more per thousand dollars of benefit, since the insurer is accepting applicants it knows nothing about medically.
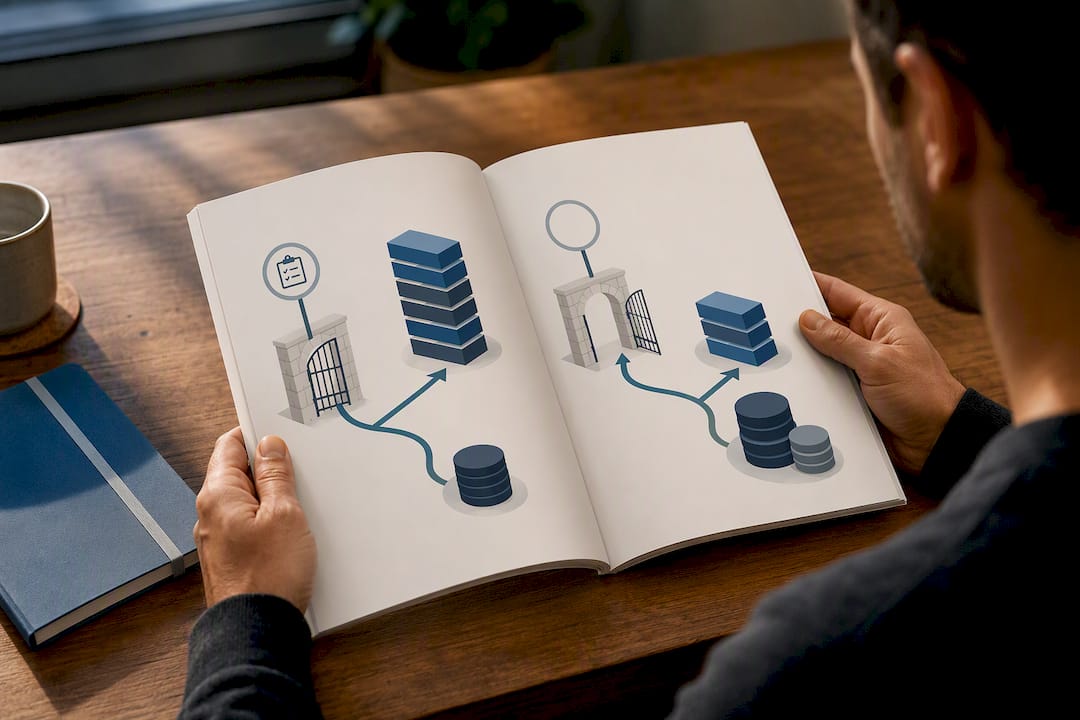
Waiting and graded benefits: Simplified issue policies rarely include a graded period; once approved, you’re covered for the full amount from day one. Guaranteed issue almost always includes a two to three year graded benefit period for death by natural causes.
Speed: Both beat traditional underwriting on timing. Many simplified issue applications get approved same day, sometimes instantly. Guaranteed issue is also fast to approve since there’s nothing to evaluate, but the coverage itself is limited during the graded window even though the policy is active immediately.
- Approval odds: conditional (simplified) vs guaranteed (guaranteed issue)
- Face amounts: higher for simplified, capped lower for guaranteed
- Premiums: lower per dollar for simplified, higher for guaranteed
- Graded benefit: rare in simplified, standard in guaranteed
- Time to coverage: same day to a few days for both, though “coverage” means different things during a graded period
How Do You Decide Between the Two?
Start with your health profile, not your preference. A quick self-audit answers most of the decision for you.
- Rate your health honestly. No major diagnoses in the past two to five years usually points toward simplified issue.
- Set your coverage target. If you need a large death benefit for income replacement or a mortgage, guaranteed issue’s caps likely won’t cover it.
- Check your timeline. If you need something in place this week regardless of outcome, guaranteed issue removes the approval risk.
- Review your application history. A recent decline for traditional or simplified coverage makes guaranteed issue the realistic fallback.
- Compare the fine print, not just the premium quote.
When you’re talking to an advisor or reading a policy outline, ask about the coverage cap, the exact length of the graded or waiting period, whether there’s a contestability clause or suicide exclusion, and whether premiums are guaranteed level or can be adjusted later. Vague answers to any of these are a red flag, and so is an application that hints you should leave out a medical condition to improve your odds. That’s not a shortcut, it’s a good way to get a claim denied later.
Pro Tip: Don’t assume you’ll be declined for simplified issue just because you have one manageable condition, like controlled high blood pressure or hypothyroidism. Insurers vary widely in what they’ll approve, so a decline from one carrier doesn’t mean guaranteed issue is your only option left.
For a broader framework on evaluating coverage options against your actual needs, this guide to comparing insurance plans walks through the kind of questions worth asking before you commit.
Applying and Timelines: What to Expect
The process itself is short for both product types, but the steps differ slightly.
- Complete the application. For simplified issue, this includes the health questionnaire. For guaranteed issue, you skip straight to personal and beneficiary details.
- Get an underwriting decision. Simplified issue applications are often decided the same day, sometimes instantly through automated systems. Guaranteed issue is approved immediately since there’s nothing to underwrite.
- Pay the first premium to activate the policy.
- Receive your policy documents, including the graded benefit terms if applicable.
Traditional, fully underwritten policies can take two to six weeks because they involve a medical exam, lab work, and a review of your full medical history. That’s the real tradeoff for a no-exam life insurance policy: speed now versus better pricing later. Cost, in either case, comes down to the same core factors: age, smoking status, coverage amount, and whether you’re buying term or whole life. Insurers also price the two product types very differently against each other, since no-exam coverage generally costs more than fully underwritten insurance at any age.
What If Neither No-Exam Option Fits?
Not everyone belongs in the no-exam category, and it’s worth knowing the alternatives before defaulting to one.
- Fully underwritten term or whole life usually gives healthier applicants the best cost per dollar of coverage, since insurers reward a completed medical exam with sharper pricing.
- Employer group life plans and supplemental workplace coverage often skip individual medical exams entirely, making them worth checking before you shop the individual market.
- Final expense policies, a smaller guaranteed whole-life product built specifically for funeral and end-of-life costs, work well when your only real need is a modest, guaranteed payout.
Why Trust This Guide: Author and Publisher Credentials
This article was prepared by Frank, drawing on regulator guidance and industry-standard underwriting practices used across the Canadian insurance market.
Easy-insured offers advisory services and insurance products related to life insurance, final expense coverage, disability and critical illness protection, and estate planning. If you’re unsure which underwriting path fits your situation, a licensed advisor can review your health history, income needs, and budget in a single conversation. Have your basic health history, current medications, and a rough coverage target ready before that call. It shortens the process considerably.
Real Scenarios, Real Recommendations
If you’re healthy but pressed for time, simplified issue is almost always the smarter first move. If you’ve had a recent serious diagnosis or a past decline, guaranteed issue is the realistic fallback, not a lesser option. The sequencing advisors recommend is simple: try simplified issue first when you can, fall back to guaranteed issue when you must. One caution either way: always answer health questions honestly. Misrepresenting your history can void a claim during the contestability period, no matter which policy you buy.
— Frank
How Easy-Insured Helps You Choose the Right Path
The company provides advisory services that include comparing simplified and guaranteed issue insurance options based on clients’ health profiles.
A consult typically starts with a short review of your health history, your coverage goal, and your timeline, then moves into specific policy options with real numbers attached, not ballpark estimates. If a small, guaranteed acceptance policy is what you actually need, Easy-insured’s final expense insurance options are built for exactly that. If your health profile points toward simplified issue instead, the same advisor can walk you through guaranteed life insurance alternatives and explain the coverage caps and graded terms in plain language before you sign anything. Reach out for a consult and bring your current medications and a rough sense of your coverage target. That’s enough to get a real conversation started.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Guaranteed Issue Life Insurance: What It Is, How It Works
- Simplified issue life insurance
- How Simplified Issue Life Insurance Works – Forbes Advisor
FAQ
What’s the Difference Between Guaranteed Issue and Simplified Issue Life Insurance?
Simplified issue requires a short health questionnaire and can result in a decline, while guaranteed issue asks no health questions and guarantees acceptance within the eligible age range, though at lower coverage caps and higher relative cost.
What Does “Guaranteed Issue” Mean in Insurance?
It means the insurer must accept your application regardless of health status, as long as you fall within the eligible age bracket, typically in exchange for smaller coverage amounts and a graded death benefit early on.
What’s the Difference Between Graded and Guaranteed Benefits?
A graded benefit limits the payout, usually to a refund of premiums plus interest, if death occurs from natural causes within the first two to three years; a guaranteed benefit refers to guaranteed acceptance into the policy itself, not the payout structure.
What Is a Guaranteed Issue Life Insurance Policy?
It’s a policy, often used for final expense coverage, that accepts applicants without medical questions or exams, trading guaranteed acceptance for lower coverage limits and higher premiums per dollar of benefit.
Can You Be Declined for Simplified Issue Life Insurance?
Yes. Insurers can decline simplified issue applicants based on their health questionnaire answers or database checks, which is the main tradeoff for its better pricing and higher coverage limits compared to guaranteed issue.